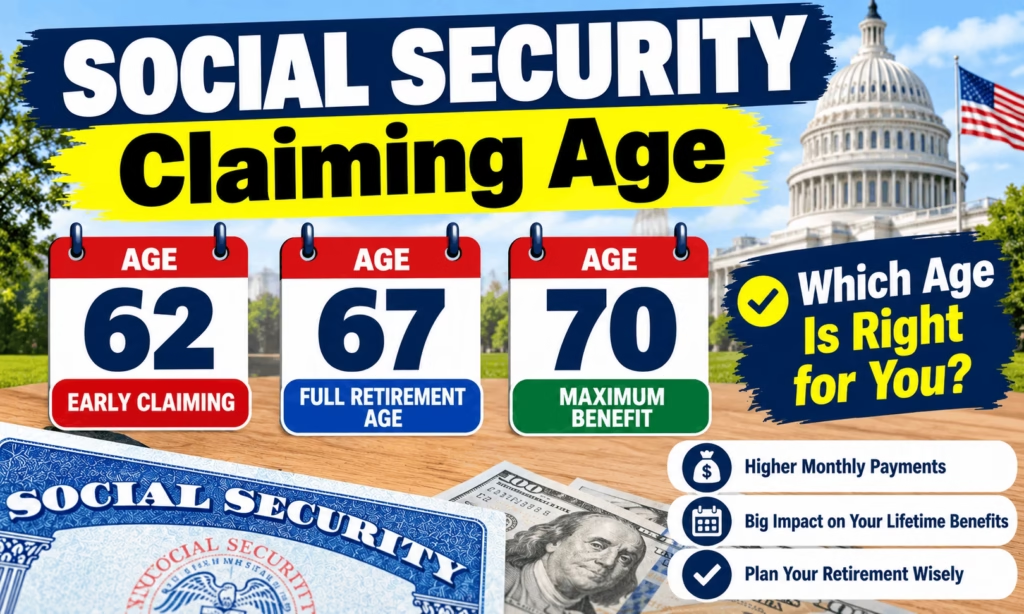
Social Security 2026 Claiming Age: If you are deciding when to claim Social Security, you may have seen headlines about “new names” for ages 62, 67 and 70. The Claiming Age Clarity Act (H.R. 5284) would change the labels the Social Security Administration (SSA) uses for those ages. It does not change the ages, the rules, or the amount of any benefit.
The bill passed the Senate without amendment on September 29, 2026, by unanimous consent, after the House passed it by voice vote in December 2025. The Government Publishing Office lists the enrolled version as dated October 9, 2026.
Social Security 2026 Claiming Age
The reasoning behind the bill is that “early,” “full” and “delayed” suggest there is a correct age to claim, when the real choice is a sliding scale. Under SSA’s rules, every month you wait between 62 and 70 raises your monthly benefit, and there is no cliff at any particular birthday.
This article covers what the new names are, what is unchanged, the current numbers for 2026 and 2027, and how to check your own figures.
What the Bill Would Rename?
The bill’s text directs the SSA to replace these terms in its rules, guidance and materials, online and in print:
| Today’s SSA term | Proposed term | Age |
| Early eligibility age | Minimum monthly benefit age | 62 |
| Full retirement age / normal retirement age | Standard monthly benefit age | 66 to 67, by birth year |
| Delayed retirement credit (as the label for waiting until 70) | Maximum monthly benefit age | 70 |
The SSA would have until the later of 12 months after enactment or January 1, 2027 to make the change. Because that deadline is tied to enactment, you may keep seeing the old terms on SSA pages for some time. The bill also says the term “delayed retirement credit” should no longer be used, but it does not supply a replacement phrase for the credit itself.
What Does Not Change?
The legislation is a terminology bill. It does not change:
- The earliest claiming age, which stays 62 for retirement benefits.
- Your full retirement age, which is 67 for anyone born in 1960 or later. SSA’s own page says it falls between 66 and 67 depending on birth year.
- The reduction for claiming before full retirement age. For people born in 1960 or later, claiming at 62 gives about 70% of the full benefit, a permanent 30% cut.
- The increase for waiting. Each month you delay past full retirement age raises your benefit, up to age 70. After 70 there is no further increase.
- How your benefit is calculated from your lifetime earnings.
The new labels carry some risk of misreading. “Minimum monthly benefit age” could sound like a guaranteed floor, and “maximum monthly benefit age” could sound like everyone at 70 gets the highest possible check. Your own payment depends on your earnings record, not on the label.
How 62, 67 and 70 Compare in Dollars?
Here is an illustration using a made-up worker whose full-retirement-age benefit is $2,000 a month. The percentages are the standard ones for someone with a full retirement age of 67. Your own figures will differ.
| Claiming age | Share of full benefit | Example monthly amount |
| 62 | About 70% | About $1,400 |
| 67 | 100% | $2,000 |
| 70 | About 124% | About $2,480 |
The 124% figure comes from delayed credits of 8% per year for three years. The bill’s House sponsors describe the gain from waiting as up to 24% above the standard benefit.
Between those ages, the gain is by the month. Claiming at 64, or at 67 years and one month, produces an amount that falls proportionally between the milestones. None of the ages is a special threshold.
Current Numbers: The 2027 COLA and Limits
The SSA announced on October 14, 2026 that benefits will rise 3.6% in January 2027. That compares with a 2.8% increase for 2026. Some figures from the SSA’s 2027 fact sheet:
- COLA: 3.6% for Social Security and SSI, with the increase starting in January 2027 benefits. It does not affect your November 2026 payment.
- Average retired-worker benefit: estimated at $2,095 before the COLA and $2,170 after it.
- Maximum benefit for a worker retiring at full retirement age: $4,188 a month in 2027, up from $4,152 in 2026.
- Maximum taxable earnings: $192,300 in 2027, up from $184,500.
- Retirement earnings test, under full retirement age: $25,560 a year in 2027 (up from $24,480). The SSA withholds $1 in benefits for every $2 earned above the limit.
- Retirement earnings test, year you reach full retirement age: $67,920 in 2027 (up from $65,160). Here $1 is withheld for every $3 earned above the limit, and only earnings before the month you reach full retirement age count.
- After you reach full retirement age: there is no earnings limit.
If you have a my Social Security account, the SSA says you can view your COLA notice online beginning in late November. Others will receive a mailed notice in December.
Why the Names Matter, According to Supporters?
Backers of the bill, including its sponsors Reps. Lloyd Smucker and Don Beyer, argue that the current terms nudge people toward the wrong conclusion. A person who hears “full retirement age” may think anything earlier is a mistake and anything later is optional, or may simply not realize that every month of delay adds to the check. The Congressional Research Service’s summary notes that researchers have found the alternative terms improve people’s understanding of retirement ages and can affect claiming intentions.
The CRS also records the other side. Some argue the current terms already inform the public about how claiming decisions affect monthly benefits. And there is a practical limit to any label change: the reasons people claim early often have nothing to do with terminology, such as health, job loss, or the need for income now.
Claiming Early Can Still Make Sense
Waiting is not right for everyone. SSA’s planning page says people choose when to apply based on what works best for them. Some apply earlier to spread payments over more years, or so family members can apply for family benefits sooner.
Things to weigh:
- Health and family longevity. Claiming early means more years of smaller checks. Waiting means fewer years of larger ones.
- Whether you are still working. Before full retirement age, benefits can be withheld if your earnings exceed the annual limit. At full retirement age, the SSA increases your monthly amount to account for the months it withheld benefits.
- Spouse and survivor benefits. For family or survivor benefits, the SSA says your amount is highest at full retirement age and does not increase if you wait longer. Your own retirement benefit does keep growing until 70.
- Medicare. If you get Medicare Part B, its premium is taken out of your monthly benefit, so your deposit can be lower than your gross benefit.
- Taxes. You may owe federal tax on your benefits, and you can ask the SSA to withhold it.
- Savings and other income. Whether you can bridge the gap to a later claiming age depends on what else you have to live on.
How to Check Your Own Numbers?
- Sign in to my Social Security. The SSA’s planning page says your account shows whether you are eligible and what you would get if you apply at different times between 62 and 70.
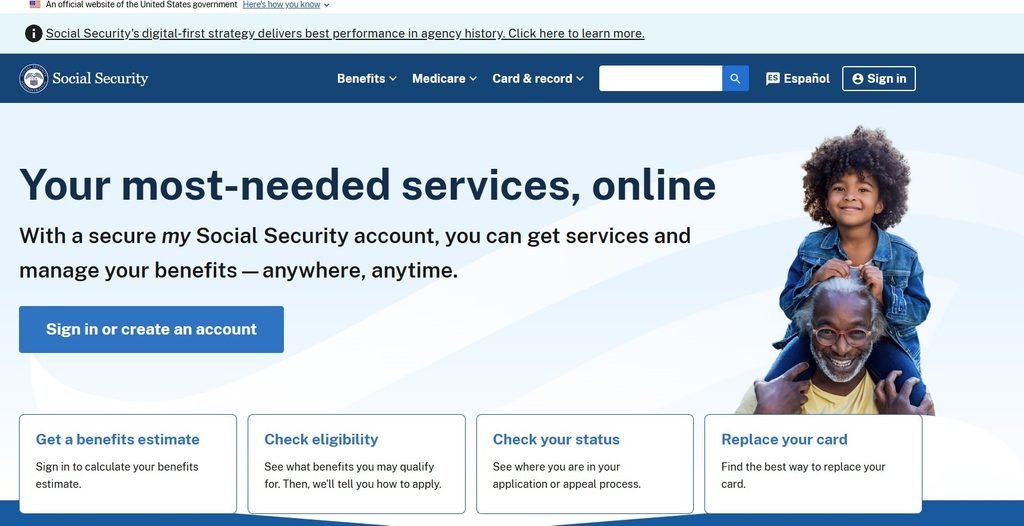
- Look up your full retirement age. Use the SSA’s full retirement age page to see yours by birth date.
- Review your earnings record. Your benefit is based on your lifetime earnings, so errors in your record can lower it.
- Check the timing rules. The SSA has a page on timing your application so your first payment arrives when you want it.
- Apply through the SSA. The SSA says that in most cases you can apply while still working.
Official Sources
Frequently Asked Questions
Is the full retirement age changing?
No. The bill only renames it. For anyone born in 1960 or later, the age is still 67.
What are the new names?
Age 62 would be the “minimum monthly benefit age,” full retirement age would be the “standard monthly benefit age,” and age 70 would be the “maximum monthly benefit age.”
Has the bill become law?
Congress passed it on September 29, 2026, and the enrolled bill is dated October 9.
Will my check change because of the new names?
No. The bill does not touch benefit formulas, reductions or increases.
When would the SSA start using the new terms?
If the bill becomes law, the SSA would have until the later of 12 months after enactment or January 1, 2027.
Can I still claim at 62?
Yes. Retirement benefits are generally available from 62 if you have worked and paid Social Security taxes for 10 years or more. For people born in 1960 or later, claiming at 62 means about 70% of the full benefit.
Does waiting past 67 raise my check?
Yes, until age 70. After 70 there is no further increase, so there is no reason to delay beyond that.
Is there a penalty for claiming a month before or after 67?
There is no cliff. The adjustment works month by month, so claiming slightly before or after full retirement age changes your benefit only slightly.
What is the 2027 COLA?
3.6%, announced October 14, 2026, starting with January 2027 benefits. The 2026 COLA was 2.8%.
How much is the average retired-worker benefit?
The SSA estimates $2,170 a month in January 2027 after the COLA, up from $2,095 before it.
What is the maximum benefit for someone retiring at full retirement age in 2027?
$4,188 a month, per the SSA’s fact sheet. Most people receive less, because the amount depends on lifetime earnings.
Will working while claiming early reduce my benefits?
It can. Before full retirement age, the SSA withholds $1 for every $2 you earn above $25,560 in 2027. In the year you reach full retirement age, it withholds $1 for every $3 above $67,920. After you reach full retirement age, there is no limit.
Where can I see my personal estimate?
Sign in to your my Social Security account.
Where do I report a Social Security scam?
Use the SSA Office of the Inspector General’s fraud reporting page, linked above.

3 thoughts on “Social Security 2026 Claiming Age: New Age Names, Same Check”